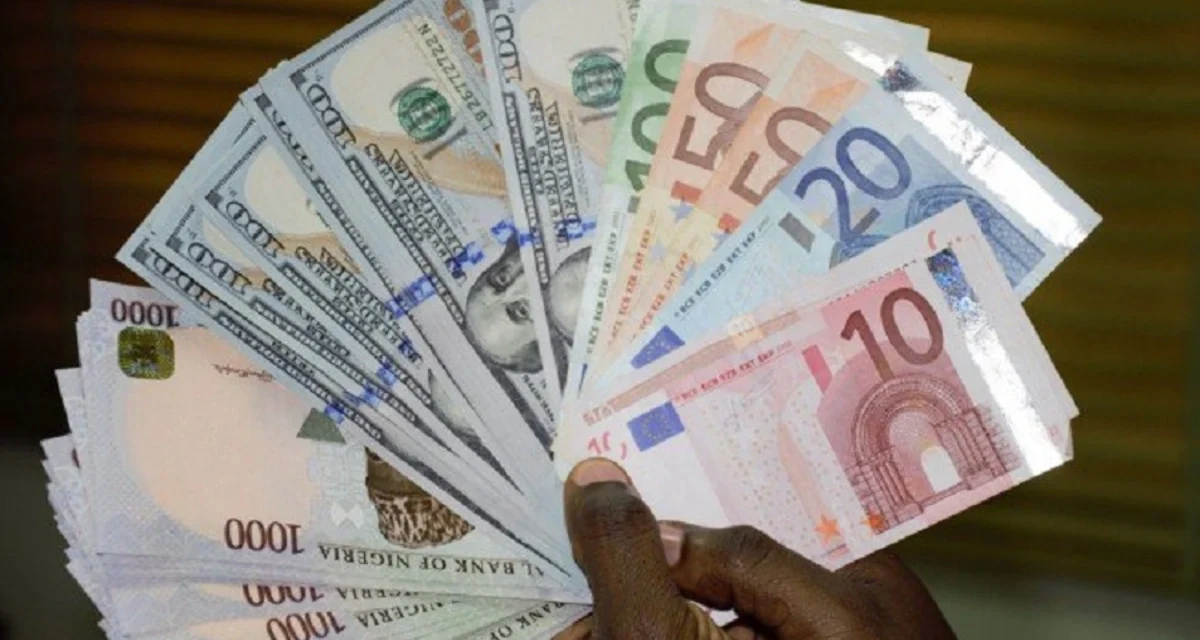

The Nigerian naira enters the month supported by rising crude oil costs, larger home oil output, and a substantial improve in overseas reserves.
Over a comparatively quick interval, larger vitality costs offered exterior assist for Nigeria’s commerce stability and the Central Bank of Nigeria’s (CBN) overseas forex holdings.
Global oil costs, pushed larger by elevated danger premia and provide disruptions, have elevated Nigeria’s overseas forex inflows.
Bonny Light promoting for $115 per barrel crude export proceeds at the moment are taking part in a important a part of the FX windfall in {dollars}, and stronger benchmark costs are offering the CBN’s money buffer to enterprise into the FX market as and when, and to fulfill import/repatriation calls for.
Domestic crude oil manufacturing has reached its highest degree in 4 years, enabling Nigeria to learn totally from the rally in worldwide benchmark costs. Production exceeded 1.53 million barrels per day, or an estimated 1.7 million barrels per day together with condensates, amid improved safety within the Niger Delta and decreased ranges of vandalism.
This output is above Nigeria’s OPEC quota and straight helps the nation’s major supply of overseas change.
The nation’s complete overseas change reserves stand at roughly $55 billion, whereas internet reserves have risen to a file $46 billion. The regular enlargement of foreign exchange reserves has maintained greenback liquidity available in the market. Net reserve power is the primary line of protection in opposition to speculative assault and near-term sharp devaluation stress.
Higher greenback revenues are strengthening the CBN’s capability to satisfy exterior debt obligations and intervene within the Nigerian Foreign Exchange Market (NFEM) to mitigate sharp declines within the naira.
CBN coverage and liquidity administration: Further aggressive open market operations (OMO) and financial tightening are preserving extra liquidity within the system subdued, making naira-denominated yields extra engaging to overseas portfolio buyers (FPIs).
Increased processing capability, together with home refineries reminiscent of Dangote, has begun to cut back overseas change demand for imported refined petrol. This represents a structural shift that would reduce the overseas change outflow related to gasoline imports, which was extra pronounced in earlier years.
Near-term outlook: The change charge has not too long ago traded throughout the N1,330–N1,370/$ vary. Higher oil revenues give the CBN better capability to restrict depreciation and stop a return to the weaker ranges recorded in earlier years.
Official interbank overseas change charges (N1,346/$) are close to the midpoint of the present consolidation vary, whereas parallel-market charges are barely larger, at N1,380/$–N1,390/$. This signifies a persistent however manageable premium. Robust home coverage charges of 23.0% and sustained capital inflows present structural assist and will assist restrict depreciation pressures.
Risks: A sudden slowdown in world oil demand or operational disruptions to Nigerian manufacturing might cut back oil-backed overseas change inflows and push spot charges beneath N1,350/$. Any renewed Niger Delta disruption would pose a right away provide danger, significantly as a result of current manufacturing beneficial properties stemmed from improved pipeline uptime slightly than new deepwater or affiliate manufacturing coming on-line.
Despite current enhancements, oil manufacturing stays beneath the statutory price range benchmark of two million barrels per day, indicating that authorities deficit financing stays a structural concern.
Upside danger for the naira: A fast improve in overseas change inflows from exterior borrowing, or additional FPI funding in native yield curves, might take a look at the decrease sure of N1,320/$.
High world crude oil costs are a optimistic macroeconomic issue for the naira. Foreign change inflows might restrict draw back stress on the forex and assist the change charge, offered crude costs stay elevated, and home manufacturing stays sturdy.
The principal concern stays a potential decline in crude costs over the long term, underscoring the significance of overseas change reforms and non-oil export diversification to keep up stability.