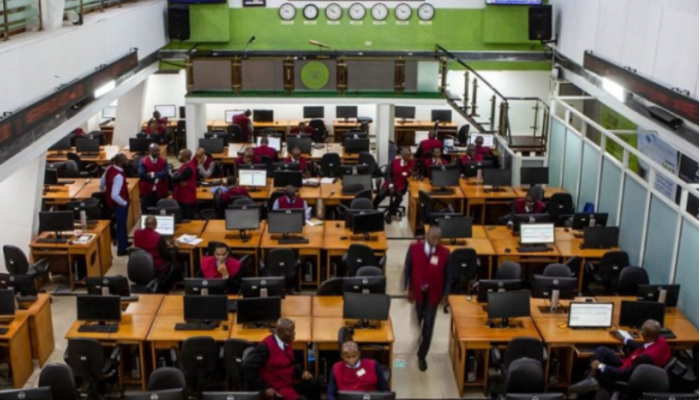
The Nigerian equities market was marginally bullish on Wednesday, reversing two consecutive days of declines amid a broad-based rally throughout mid and small-cap stocks.
Although the important thing market drivers declined barely, optimistic market breadth means that momentum favored the bulls.
The Nigerian inventory market (NGX) has skilled selloffs and adverse retracements following multi-year highs in latest weeks.
Institutional and retail buyers typically understand vital good points after a considerable rally in the NGX All-Share Index (ASI), significantly when key market-psychology thresholds are breached.
However, the structural and year-to-date bull market remains intact, with vital good points made earlier in the yr, particularly in the Oil & Gas sector amid excessive crude oil costs. The CBN and the fixed-income surroundings nonetheless assist portfolio rebalancing between fixed-income securities and equities.
Tier-1 banking stocks, together with FUGAZ, stay vital contributors to market liquidity. The banks’ recapitalization workouts, mandated by the CBN, are driving adjustments in their capital bases. However, sizable company transactions and IPOs, such because the Dangote Petroleum Refinery IPO, additionally appeal to substantial retail and institutional liquidity.
Investors at the moment are constructing positions in anticipation of Q3 financials launch. Markets noticed some early shopping for curiosity in dividend-paying Tier 1 banks, insurers and monetary providers stocks (AFRIPRUD (+5.88%) and WEMABANK (+2.65%), aligning with strategic shopping for of mid- to large-cap corporations with stable fundamentals.
The heavyweight banking stocks GTCO (+0.23%) and UBA (+0.12%) recorded solely modest good points. Given their substantial affect on the capitalization-weighted NGX-ASI, the subdued efficiency of those stocks weighed on the primary index, limiting the visibility of the relative power proven by second-tier and mid-cap stocks.
Some buyers started taking earnings in banking and large-cap stocks following a powerful year-to-date efficiency. Institutional funds usually cut back portfolio weightings forward of Q3 company earnings releases till cash-flow statements validate the underlying margin-expansion fundamentals.
Sector Rotation: Capital is shifting from comparatively oversold sectors, equivalent to Banking and Commercial, to lagging or undervalued sectors, together with Insurance, Consumer, and chosen Agriculture and Logistics equities.
Technical motion
The market retraced from an all-time psychological excessive of 255,000 – 247,500 worth stage. Year to this point, it remains considerably greater at +59.20%; the present correction seems wholesome relative to the broader pattern and doesn’t essentially point out a systemic reversal.
Strategic motion plan for fairness buyers
Rebalance Sector Allocation: Gradually cut back publicity to overextended Tier-1 stocks which have fallen to key technical assist ranges, and take into account reallocating funds to undervalued, high-dividend-yield counters.
Set Staggered Entry Points (NCA): Use accessible proceeds to naira-cost common into high-conviction corporations with sturdy fundamentals in Oil & Gas, Agriculture, and high quality banking stocks throughout market pullbacks.
Further profit-taking and consolidation are prone to proceed till fixed-income yields decline or inflation falls sufficiently to justify financial easing. Trading volumes had been blended as giant institutional consumers entered blue-chip stocks throughout worth dips.
Market recapitalization and structural reforms present a stable basis for fundamentals to achieve momentum after interest-rate cycles peak. Companies with sturdy stability sheets, sturdy foreign-income prospects, and excessive dividend yields are higher positioned to face up to the correction interval.