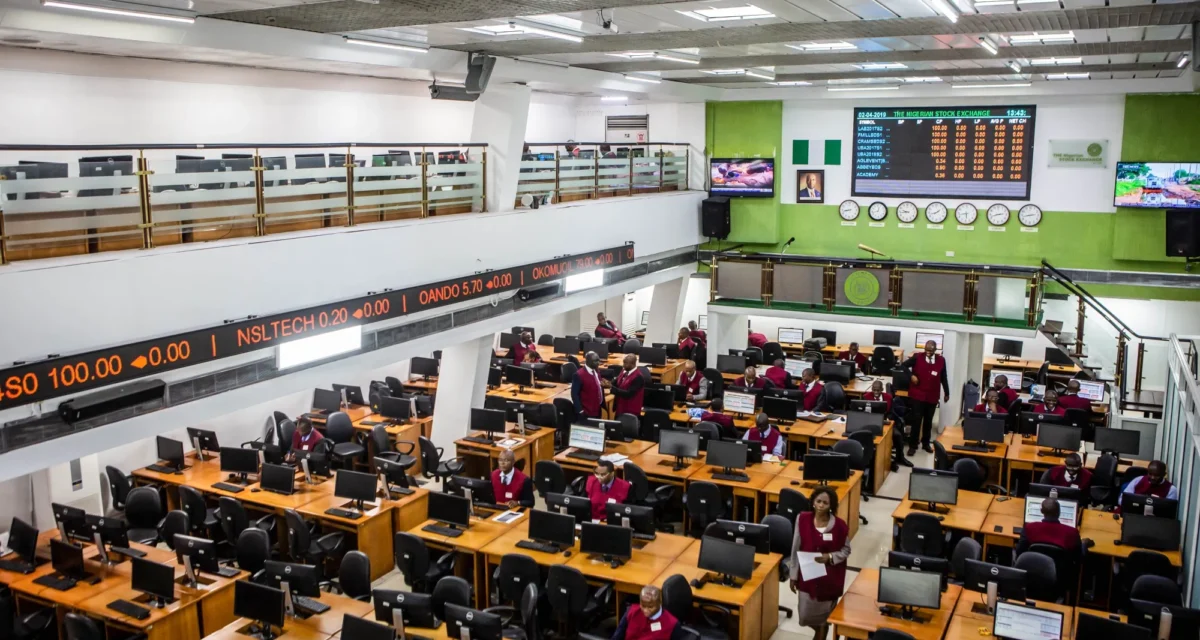

Nigerian equities closed decrease for the third straight week, with the benchmark NGX All-Share Index (ASI) declining 0.33% to shut at 247,539.73 factors from 248,363.55 factors.
Losses in banking stocks, led by Zenith Bank, GTCO and Fidelity Bank, outweighed beneficial properties in oil and gasoline names corresponding to Aradel Holdings.
Market capitalisation fell by roughly N534.77 billion to N160.73 trillion, bringing the market’s year-to-date return to 59.07%.
Livestock Feeds emerged as the week’s standout performer, surging 44.49% from N13.15 to N19.00. UPDC Real Estate Investment Trust recorded the steepest decline, falling 11.88% to N21.15 from N24.00.
What the knowledge is saying:
Market breadth turned optimistic regardless of the index decline, with 50 equities appreciating in value, increased than the 24 recorded the earlier week. Thirty equities depreciated, decrease than the 54 recorded beforehand, whereas 66 equities remained unchanged, down from 68 the week earlier than.
A complete turnover of 1.659 billion shares value N98.088 billion was traded in 184,632 offers, in contrast with 2.715 billion shares valued at N158.280 billion in 209,986 offers the earlier week.
- The Financial Services Industry led exercise by quantity, with 1.083 billion shares valued at N48.967 billion in 86,994 offers. That contributed 65.31% of whole quantity and 49.92% of whole worth.
- The Agriculture Industry adopted with 129.650 million shares value N2.182 billion in 8,650 offers.
- The ICT Industry ranked third with 87.909 million shares value N6.964 billion in 19,017 offers.
The prime three equities by quantity, Access Holdings, UBA and Livestock Feeds, accounted for 413.964 million shares value N12.158 billion in 18,365 offers. That represents 24.96% of whole quantity and 12.40% of whole worth.
Sectoral efficiency:
Sector efficiency was combined, with banking dragging on the market whereas oil and gasoline led the gainers.
- The NGX Oil/Gas Index recorded the strongest acquire amongst the primary sector indices, up 3.13% to six,194.00 factors from 6,005.98 factors.
- The NGX Commodity Index rose 2.36% to 1,937.41 factors from 1,892.68 factors.
- The NGX Consumer Goods Index edged up 0.09% to 4,036.97 factors from 4,033.36 factors, whereas the NGX Industrial Goods Index was just about flat, up 0.004% to 10,442.95 factors.
- The NGX Insurance Index slipped 0.14% to 1,079.57 factors from 1,081.10 factors.
- The NGX Banking Index recorded the steepest sectoral decline, down 3.15% to 2,532.47 factors from 2,614.79 factors. The NGX AFR Bank Value Index fell 3.80%.
The NGX Corporate Governance Index declined 2.39% to 7,239.74 factors from 7,416.72 factors.
Year thus far, the NGX Oil/Gas Index leads with a 131.96% return, adopted by the Industrial Goods Index at 83.97%. The Insurance Index stays adverse at -9.23%.
Top 10 Best-Performing Stocks:
- Livestock Feeds Plc: N19.00, up 44.49% from N13.15.
- E-Tranzact International Plc: N17.30, up 42.98% from N12.10.
- Multi-Trex Integrated Foods Plc: N0.60, up 42.86% from N0.42.
- Austin Laz & Company Plc: N2.92, up 32.73% from N2.20.
- Omatek Ventures Plc: N1.60, up 19.40% from N1.34.
- Fortis Global Insurance Plc: N1.90, up 13.10% from N1.68.
- Guinness Nigeria Plc: N423.00, up 9.93% from N384.80.
- Neimeth International Pharmaceuticals Plc: N7.65, up 9.29% from N7.00.
- Aradel Holdings Plc: N1,499.90, up 8.93% from N1,377.00.
- VFD Group Plc: N13.30, up 8.13% from N12.30.
Top 10 worst-performing stocks:
- UPDC Real Estate Investment Trust: N21.15, down 11.88% from N24.00.
- Nigerian Enamelware Plc: N36.65, down 9.95% from N40.70.
- NASCON Allied Industries Plc: N171.00, down 9.48% from N188.90.
- Trans-Nationwide Express Plc: N2.70, down 9.09% from N2.97.
- DwellingTrust Mortgage Bank Plc: N2.93, down 8.44% from N3.20.
- SUNU Assurances Nigeria Plc: N3.00, down 7.69% from N3.25.
- Critical Minerals Financing Corp Plc: N3.31, down 7.54% from N3.58.
- Zenith Bank Plc: N126.00, down 6.46% from N134.70.
- PZ Cussons Nigeria Plc: N64.50, down 5.15% from N68.00.
- Guaranty Trust Holding Company (GTCO): N124.80, down 5.10% from N131.50.
What stands out:
Several of final week’s largest decliners rebounded. Aradel Holdings, which fell 10% to N1,377.00 the week earlier than, gained 8.93% to N1,499.90, whereas VFD Group recovered 8.13% after an 8.89% loss.
- Livestock Feeds prolonged a pointy rally, rising 44.49% after a 47.75% acquire the earlier week. Over the two weeks, the inventory has risen from N8.90 to N19.00, up about 113%.
- E-Tranzact rose 42.98% after a ten.00% acquire final week, whereas Omatek Ventures gained 19.40%.
- UPDC REIT reversed course, falling 11.88% after rising 16.22% the earlier week, whereas Critical Minerals shed an extra 7.54% after final week’s 20.27% drop.
- Banking weak spot was seen in the decliners, with Zenith Bank down 6.46% and GTCO down 5.10%.
Nairametrics reported that the market had dipped in mid-October at the same time as the broader bull run remained intact, and that Aradel and Oando had lifted the market for a second day on October 15.
Dividend value changes:
Three corporations had their costs adjusted for dividends throughout the week, which affected their weekly returns.
- PZ Cussons Nigeria: ex-dividend on October 12, N2.50 dividend, reference value adjusted to N65.50 from N68.00 (3.68%).
- GTCO: ex-dividend on October 13, N1.00 dividend, reference value adjusted to N130.00 from N131.00 (0.76%).
- Stanbic IBTC Holdings: ex-dividend on October 16, N4.50 dividend, reference value adjusted to N163.50 from N168.00 (2.68%).
PZ Cussons’ 5.15% decline and GTCO’s 5.10% decline embody these changes, which replicate dividend entitlements being faraway from the share value and don’t essentially point out promoting strain.
Corporate actions:
The buying and selling image of UH Real Estate Investment Trust modified from UHOMEREIT to UHREIT.
What you must know:
The ASI fell for a 3rd straight week, with weekly losses of 0.52%, 0.97% and 0.33%, although the newest decline was the smallest.
- The ASI closed inside a slim band of 247,513.63 to 247,736.24 factors throughout the week.
- Market capitalisation was N160.73 trillion on Friday, down about N108.70 billion from Thursday.
- Positive breadth, with 50 gainers in opposition to 30 decliners, reveals that the index fall was pushed by large-cap banking names reasonably than broad promoting.
- Turnover worth fell about 38% from the earlier week to N98.088 billion.
Looking forward, “we expect market sentiment to improve, supported by (1) bargain hunting following recent price declines, (2) anticipation of Q3 earnings releases and (3) positioning ahead of upcoming dividend qualification dates, which could drive selective buying interest,” analysts at Cordros Securities Limited stated in their Weekly Economic and Market Report.