
Mastercard launched stablecoin safety to present banking and finance companies. The safety characteristic comes with instruments to detect fraudulent actions, scams, and potential violations of sanctions legal guidelines related to stablecoin transactions.
In doing so, this offers monetary establishments with the chance to consider potential dangers prior to suspicious transactions being processed.
With extra advanced kinds of stablecoin funds changing into more and more widespread, early detection of potential issues is changing into extra vital.
These fee chains can complicate danger evaluation and make post-settlement monitoring much less efficient.
Borderless.xyz and Keyrails are among the many first individuals to help the brand new product’s North American launch, and Mastercard expects to provide it globally starting in 2027.
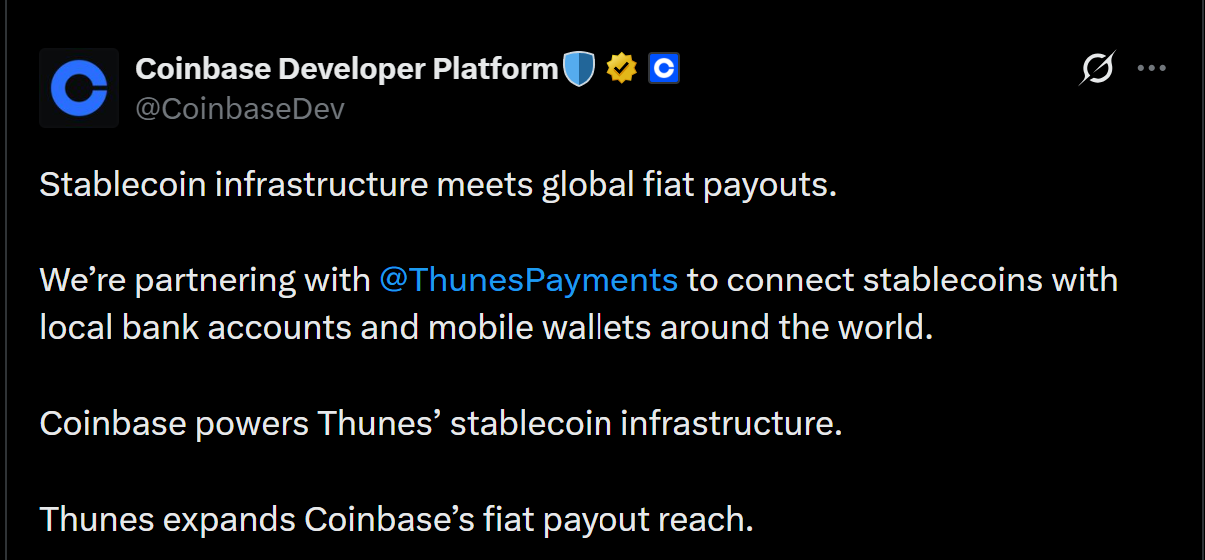
Coinbase and Thunes broaden stablecoin payout attain
Following the push to make stablecoin funds safer, Coinbase and Thunes are working collectively to remedy one other major concern in enabling the widespread adoption of stablecoin funds. This is completed by offering recipients with instant entry to stablecoin funds at their native checking account or cellular pockets.
Through their joint effort, Coinbase’s stablecoin-enabled fee methods will join immediately to Thunes’ Direct Global Network. This offers direct connections to over 140 nations and 90 completely different currencies through financial institution accounts and cellular wallets.
Ultimately, whether or not Coinbase and Thunes’ actions will end in important adoption will depend upon a number of elements. This consists of the provision of payout choices, the efficiency of the payout course of itself, and precise utilization ranges amongst retailers, prospects, and recipients.
Could higher infrastructure drive stablecoin adoption?
Better infrastructure is vital to changing higher stablecoin adoption into greater quantity fee exercise. Mastercard is bettering transaction screening, whereas Coinbase and Thunes are increasing entry to native payouts.
Together, these initiatives handle two major barriers stopping wider adoption of stablecoin safety and accessibility. Institutions can assess dangers earlier and attain recipients by native banks and cellular wallets.
As such, these enhancements may make cross-border transactions simpler for each customers and enterprise homeowners.
However, stronger infrastructure doesn’t assure sustained demand. Allium’s 2026 data reveals fee volumes rising whereas stablecoin provide stays largely flat.
Notably, the info means that current quantities of stablecoins are rising in frequency as they proceed to flow into. So, if repeated utilization will increase together with settled worth, then stablecoins may expertise broader enchantment exterior of the crypto ecosystem.
Conversely, if precise utilization fails to enhance regardless of improved infrastructure improvement, then infrastructure progress might outpace precise utilization.
Final Summary
- Mastercard’s Stablecoin Security may enhance belief by screening fraud and sanctions dangers earlier than settlement.
- Coinbase and Thunes broaden stablecoin payouts, however adoption relies on actual transaction demand.